Can You Get a DSCR Loan With Bad Credit? Here's What Investors Need to Know
Many real estate investors assume they need excellent credit to qualify for a DSCR loan.
The truth is, you don't.
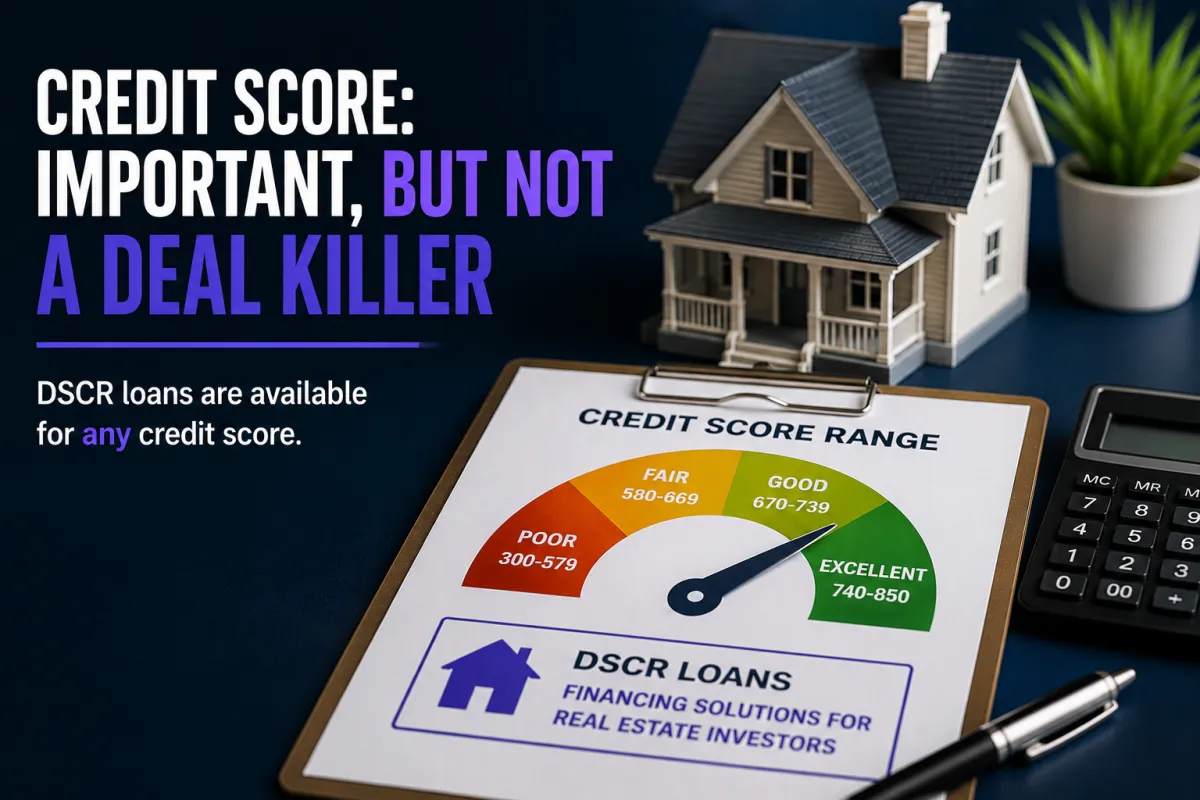
While a higher credit score can help you qualify for better loan terms, a lower score doesn't automatically mean your loan will be denied. In fact, many DSCR loan programs are designed to accommodate investors with less-than-perfect credit.
Credit Matters—But It's Only One Piece of the Puzzle
Your credit score influences the terms you're offered, but it's rarely the only factor a lender considers.
In most cases, a lower credit score may result in:
A lower maximum loan-to-value (LTV), meaning you may be able to borrow less against your property's value.
A higher interest rate, which can increase your monthly payment.
Fewer available loan options compared to borrowers with stronger credit.
That doesn't mean financing is out of reach. It simply means the right loan program becomes even more important.
Every Lender Has Different Credit Guidelines
One of the biggest misconceptions about DSCR loans is that every lender has the same credit requirements.
They don't.
Some lenders specialize in borrowers with stronger credit profiles, while others offer programs specifically designed for investors with lower credit scores. The difference between an approval and a denial often comes down to choosing the lender whose guidelines best fit your situation.
The Goal Is Finding the Right Match
If your credit score isn't perfect, don't assume your financing options are limited.
Instead of asking, "Will I qualify?" ask, "Which lender is the best fit for my loan scenario?"
That's where working with an investor financing specialist can make a significant difference. By comparing multiple wholesale lenders and loan programs, it's often possible to find financing that aligns with your credit profile, property, and investment goals.
The Bottom Line
A lower credit score doesn't automatically disqualify you from getting a DSCR loan.
It may affect your interest rate, maximum cash-out, or available loan programs—but it doesn't necessarily prevent you from financing or refinancing your investment property.
Before assuming the answer is "no," make sure you've explored all of your options. The right lender and the right loan product can often make the difference between a declined application and a successful closing.
Applying For a DSCR Loan?
If you're planning to apply for a DSCR loan, call me, Brian Smith, at 855-774-3160 or schedule a quick WHOLESALE RATE SHOPPER call on my calendar by clicking here.
On the call, you and I will shop your loan scenario with 100+ wholesale lenders to find the ones accepting your scenario and the wholesale rates they're offering you. No credit check needed.
We'll find the lenders offering you the best rate and lowest payment for your DSCR loan scenario, even if your investment property is listed for sale, vacant, bought yesterday, or behind on payments. With my DSCR loan, you can maximize your property's cash flow and bottom line.
Please allow 15 minutes so you can see all of the wholesale rates and loan terms available to you. Have pen, paper, and calculator ready when we talk.
If you do not like the loan terms I offer you, you are under no obligation to move forward.
If you like what you see and think I'm the right expert to help you with your investment property financing, we can start by reserving a spot for you on my Funding Calendar for a tentative date to fund your loan.
If you choose another loan source, the information you receive on our call will still help you.
Call 855-774-3160 or schedule a quick WHOLESALE RATE SHOPPER call on my calendar by clicking here. No credit check. No cost. No obligation.