Discount Points Explained: Understanding the Mortgage Rate Seesaw
One of the biggest misconceptions about mortgage rates is that every loan comes with one interest rate.
It doesn't.
In reality, lenders typically offer a range of interest rates, each with its own upfront cost. Choosing the right combination of rate and cost can save—or cost—you thousands of dollars over the life of your loan.
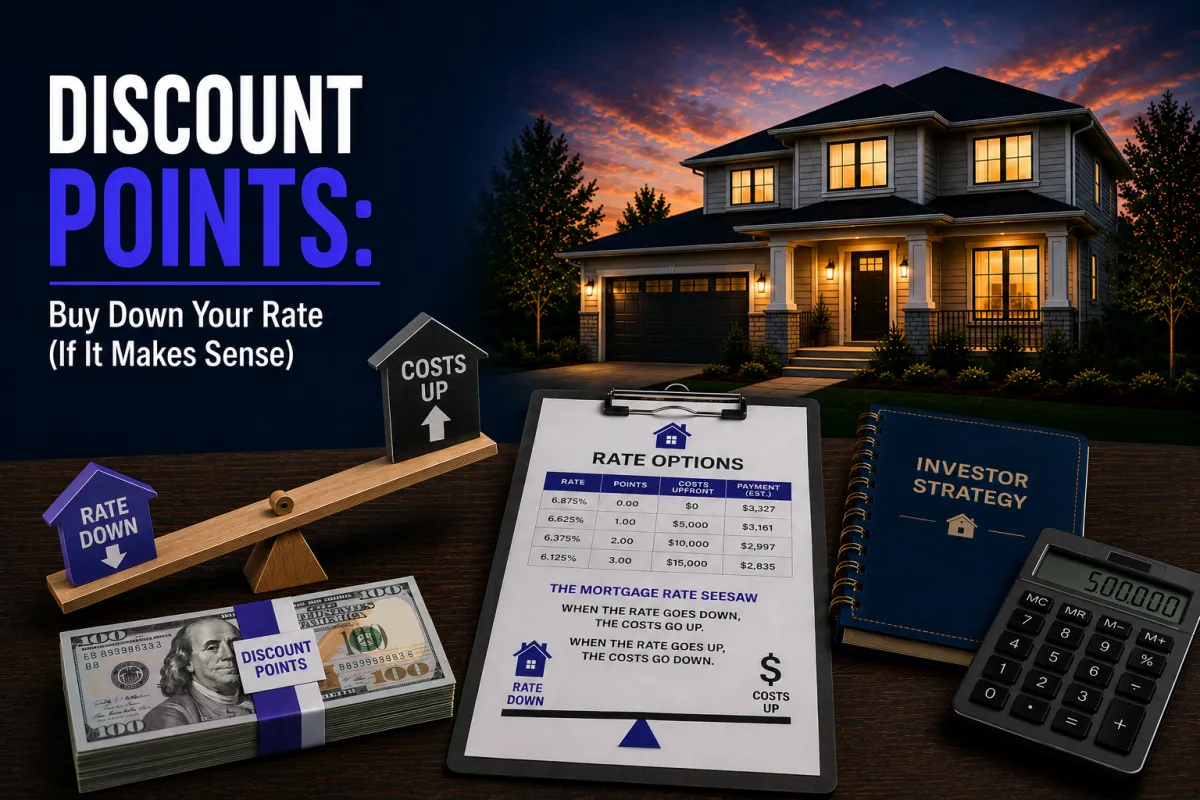
I like to call this The Mortgage Rate Seesaw.
As one side goes down, the other goes up.
Lower interest rate = Higher upfront cost
Higher interest rate = Lower upfront cost
Understanding this relationship helps you choose the loan that's best for your investment strategy—not just the lowest advertised rate.
What Are Discount Points?
Discount points are optional fees you pay at closing to obtain a lower interest rate.
One discount point equals 1% of the loan amount.
For example:
A $500,000 loan with one discount point costs $5,000 at closing.
In exchange, the lender offers a lower interest rate, which reduces your monthly mortgage payment.
The Mortgage Rate Seesaw
Imagine a seesaw.
As the interest rate goes down, the cost of obtaining that rate goes up.
As the interest rate goes up, the cost goes down.
In some cases, choosing a slightly higher interest rate may even eliminate discount points altogether—or provide a lender credit that helps offset your closing costs.
Most DSCR loan programs offer several pricing options, allowing you to choose the balance that works best for your goals.
When Paying Discount Points Makes Sense
Buying down your interest rate may be a smart financial decision if:
You plan to keep the property for many years.
Lower monthly payments significantly improve your cash flow.
The monthly savings will eventually exceed the upfront cost.
For long-term buy-and-hold investors, paying points can produce meaningful savings over time.
When It May Not Make Sense
Discount points aren't always the right choice.
If you expect to refinance, sell the property, or pay off the loan within a few years, you may never recover the upfront cost.
In that case, choosing a slightly higher interest rate with lower—or even zero—discount points may leave you in a better financial position.
Typical Discount Point Range
Most DSCR loan programs offer pricing options ranging from:
0.00% to approximately 3.00% discount points
The exact amount depends on market conditions, your credit profile, loan-to-value, DSCR ratio, and the specific lender.
Compare More Than Just the Interest Rate
Many investors make the mistake of asking only one question:
"What's my interest rate?"
A better question is:
"What are all of my rate options?"
Review several pricing scenarios side by side so you can compare:
Interest rate
Discount points
Monthly payment
Cash out
Seeing the complete picture makes it much easier to determine which loan structure provides the greatest overall value.
The Bottom Line
There isn't one "best" interest rate.
There's only the rate that's best for your investment strategy.
Whether your priority is minimizing closing costs, maximizing monthly cash flow, or lowering your long-term borrowing costs, understanding the Mortgage Rate Seesaw helps you make a more informed decision.
Before locking your loan, ask your lender to show you multiple rate-and-cost scenarios. A few extra minutes comparing options today could save you thousands of dollars tomorrow.
Applying For a DSCR Loan?
If you're planning to apply for a DSCR loan, call me, Brian Smith, at 855-774-3160 or schedule a quick WHOLESALE RATE SHOPPER call on my calendar by clicking here.
On the call, you and I will shop your loan scenario with 100+ wholesale lenders to find the ones accepting your scenario and the wholesale rates they're offering you. No credit check needed.
We'll find the lenders offering you the best rate and lowest payment for your DSCR loan scenario, even if your investment property is listed for sale, vacant, bought yesterday, or behind on payments. With my DSCR loan, you can maximize your property's cash flow and bottom line.
Please allow 15 minutes so you can see all of the wholesale rates and loan terms available to you. Have pen, paper, and calculator ready when we talk.
If you do not like the loan terms I offer you, you are under no obligation to move forward.
If you like what you see and think I'm the right expert to help you with your investment property financing, we can start by reserving a spot for you on my Funding Calendar for a tentative date to fund your loan.
If you choose another loan source, the information you receive on our call will still help you.
Call 855-774-3160 or schedule a quick WHOLESALE RATE SHOPPER call on my calendar by clicking here. No credit check. No cost. No obligation.