DSCR Loan Prepayment Penalties: When They Save You Money (And When They Don't)
Many real estate investors hear the words "prepayment penalty" and immediately assume it's a bad thing.
In reality, prepayment penalties are a standard feature of DSCR loan programs. When chosen wisely, they can actually help lower your interest rate and improve your property's monthly cash flow.
The key is selecting a prepayment penalty that matches your investment strategy.
What Is a Prepayment Penalty?
A prepayment penalty is a fee that applies if you:
Pay off your loan early
Refinance your loan
Sell the property
during a specified period after closing.
Depending on the loan program, that period is typically one to five years.
Once the penalty period expires, you can refinance or sell without paying the fee.
Why Do Lenders Offer Lower Rates?
A prepayment penalty gives the lender greater confidence that the loan will remain in place for a certain period of time.
Because of that added certainty, many lenders reward borrowers with better pricing.
Generally speaking:
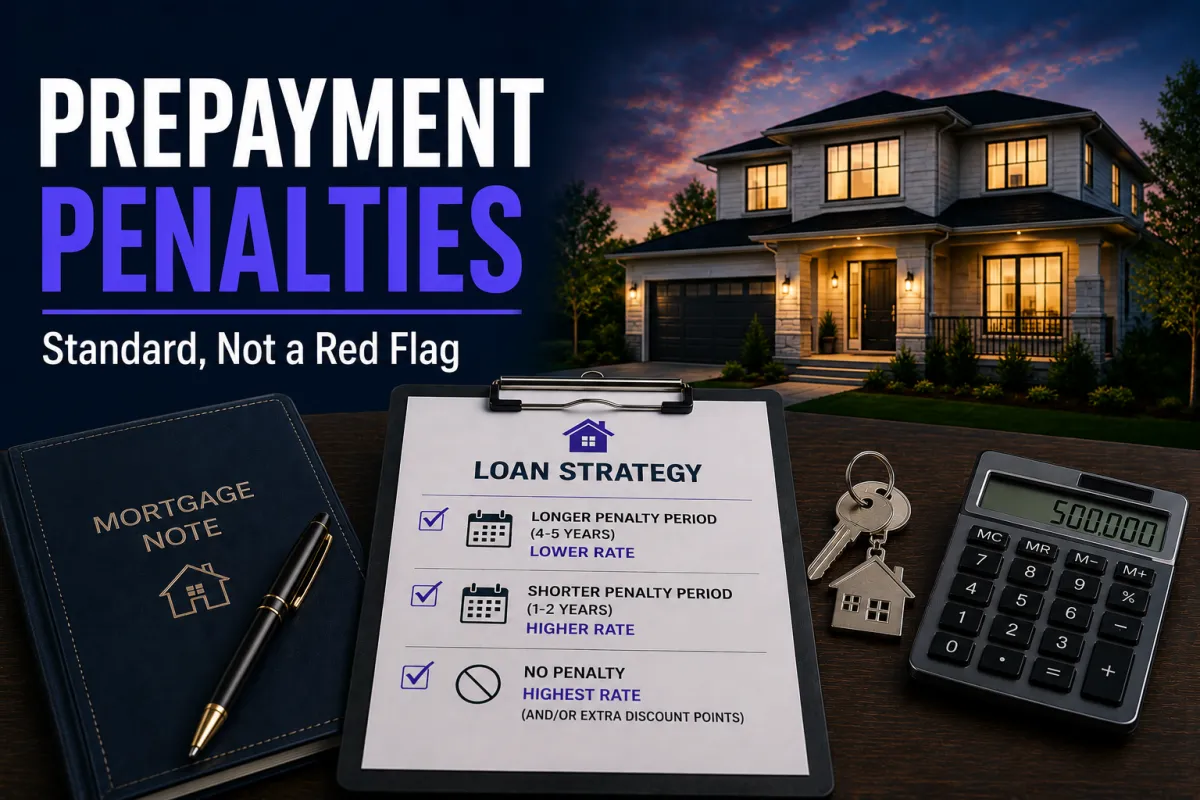
Longer prepayment penalty (4–5 years) = Lower interest rate
Shorter prepayment penalty (1–2 years) = Slightly higher interest rate
No prepayment penalty = Highest interest rate and/or additional discount points
Which Option Is Best?
The right answer depends on your investment plan.
Long-Term Buy-and-Hold Investors
If you expect to own the property (and keep the loan) for five years or longer, choosing a longer prepayment penalty often makes financial sense.
You'll typically receive a lower interest rate, resulting in lower monthly payments and stronger cash flow over the time you own the property.
Investors Planning to Sell or Refinance
If you expect to refinance when rates fall, sell the property, or complete a BRRRR strategy within the next few years, a shorter prepayment penalty—or no penalty at all—may be worth the higher interest rate.
Paying slightly more each month could save you a much larger penalty later.
Don't Automatically Choose the Lowest Rate
Many investors focus only on the interest rate without considering how long they plan to keep the loan.
A lower rate isn't always the best value if you expect to refinance or sell before the penalty expires.
Likewise, paying a higher rate for no penalty may be unnecessary if you're planning to hold the property for many years.
The Bottom Line
A prepayment penalty isn't a red flag—it's simply another tool that affects loan pricing.
The best choice is the one that matches your investment strategy.
Before locking your loan, compare the available prepayment options and calculate how each one affects your monthly payment and long-term costs. A small decision today can save—or cost—you thousands of dollars over the life of the loan.
Applying For a DSCR Loan?
If you're planning to apply for a DSCR loan, call me, Brian Smith, at 855-774-3160 or schedule a quick WHOLESALE RATE SHOPPER call on my calendar by clicking here.
On the call, you and I will shop your loan scenario with 100+ wholesale lenders to find the ones accepting your scenario and the wholesale rates they're offering you. No credit check needed.
We'll find the lenders offering you the best rate and lowest payment for your DSCR loan scenario, even if your investment property is listed for sale, vacant, bought yesterday, or behind on payments. With my DSCR loan, you can maximize your property's cash flow and bottom line.
Please allow 15 minutes so you can see all of the wholesale rates and loan terms available to you. Have pen, paper, and calculator ready when we talk.
If you do not like the loan terms I offer you, you are under no obligation to move forward.
If you like what you see and think I'm the right expert to help you with your investment property financing, we can start by reserving a spot for you on my Funding Calendar for a tentative date to fund your loan.
If you choose another loan source, the information you receive on our call will still help you.
Call 855-774-3160 or schedule a quick WHOLESALE RATE SHOPPER call on my calendar by clicking here. No credit check. No cost. No obligation.