How 40-Year and Interest-Only Loans Can Increase Your Rental Property Cash Flow
When refinancing an investment property, many investors automatically choose a 30-year mortgage.
That may not be the best option.
If your goal is to maximize monthly cash flow, a 40-year loan or an interest-only payment option could significantly reduce your monthly mortgage payment—putting more money back into your business every month.
Cash Flow Builds Wealth
Every dollar you save on your monthly mortgage payment is another dollar you can use to:
Buy another investment property
Renovate an existing rental
Build your cash reserves
Pay down high-interest debt
Increase your monthly profit
That's why many experienced investors focus on monthly payment, not just interest rate.
How a 40-Year Loan Helps
A 40-year mortgage spreads the loan repayment over a longer period than a traditional 30-year loan.
Because the principal is repaid over more years, the monthly payment is typically lower.
For investors whose primary goal is maximizing cash flow, that lower payment can make a meaningful difference.
What About Interest-Only Loans?
An interest-only loan allows you to make payments that cover only the interest for a specified period.
Because you're not paying principal during that time, your monthly payment can be substantially lower.
This option can be especially attractive for investors who want to:
Maximize monthly cash flow
Improve returns on leveraged properties
Preserve capital for future investments
Complete renovations before refinancing or selling
A Simple Example
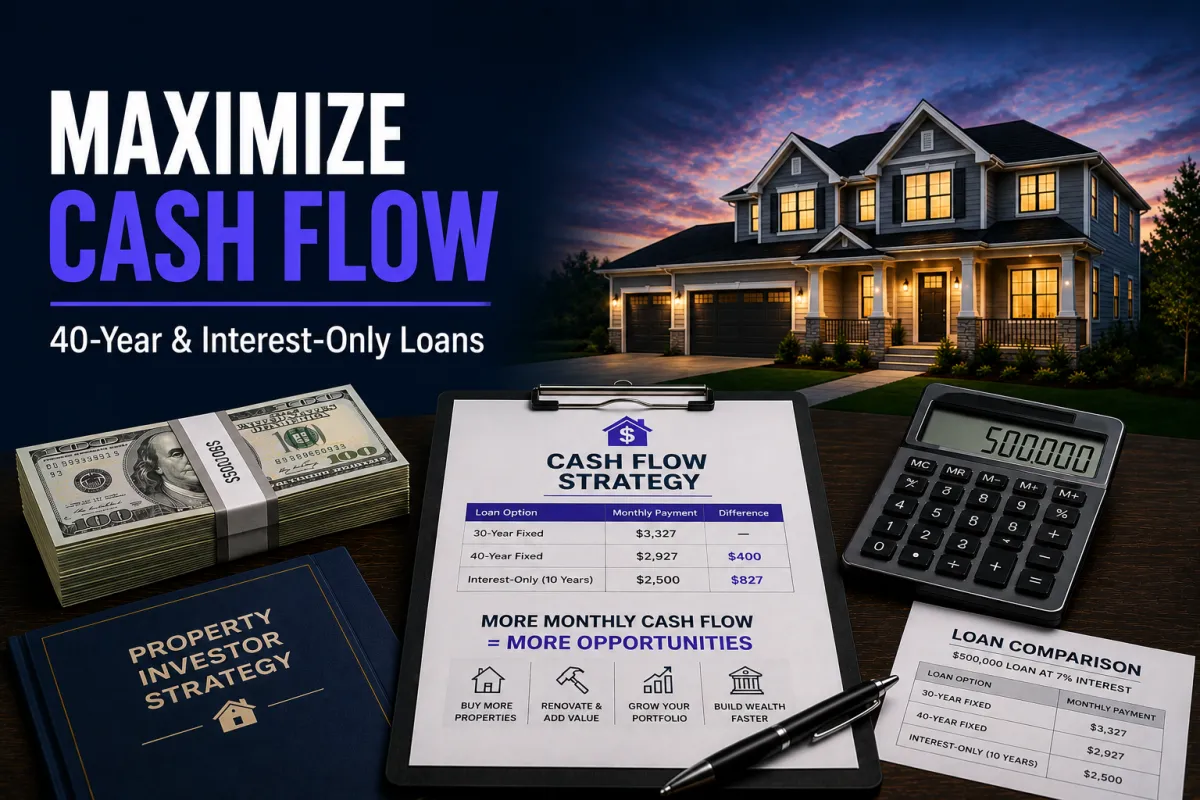
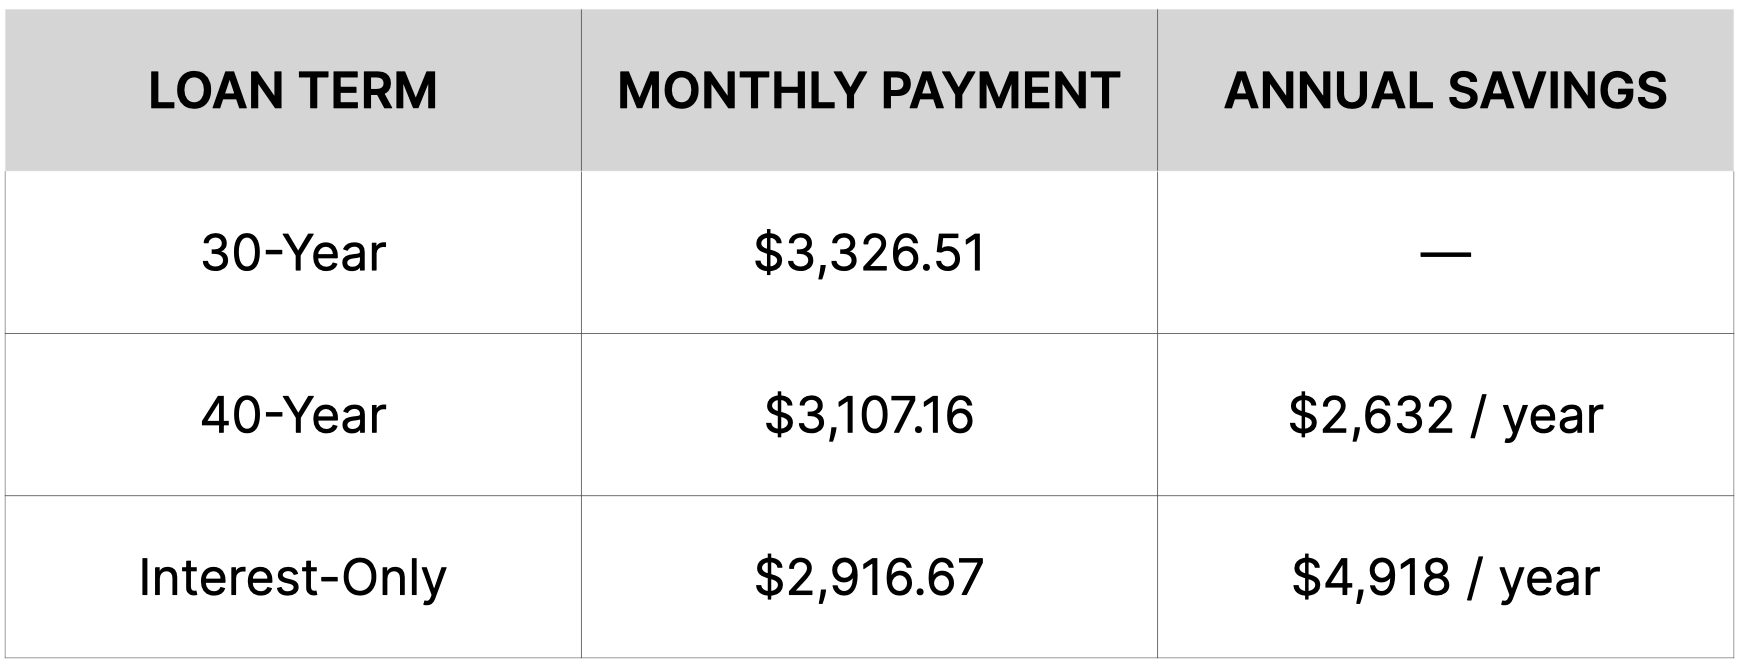
On a $500,000 loan at a 7% interest rate, choosing a 40-year term lowers your monthly payments by $219 freeing up more than $2,600 in additional annual cash flow. Choosing an interest-only option lowers your monthly payments by $409 and creates nearly $5,000 in additional annual cash flow.
That's money you can reinvest into your portfolio instead of sending to your lender each month.
Not Every Lender Offers These Options
Many banks and mortgage companies only offer traditional 30-year loan programs.
Others provide 40-year terms, interest-only options, or both.
The difference in available loan products can have a major impact on your property's monthly cash flow.
The Bottom Line
Choosing the right loan isn't always about finding the lowest interest rate.
It's about finding the loan structure that best supports your investment strategy.
If maximizing monthly cash flow is your priority, ask whether 40-year and interest-only options are available. The right loan program could significantly improve your property's performance without changing the property itself.
Applying For a DSCR Loan?
If you're planning to apply for a DSCR loan, call me, Brian Smith, at 855-774-3160 or schedule a quick WHOLESALE RATE SHOPPER call on my calendar by clicking here.
On the call, you and I will shop your loan scenario with 100+ wholesale lenders to find the ones accepting your scenario and the wholesale rates they're offering you. No credit check needed.
We'll find the lenders offering you the best rate and lowest payment for your DSCR loan scenario, even if your investment property is listed for sale, vacant, bought yesterday, or behind on payments. With my DSCR loan, you can maximize your property's cash flow and bottom line.
Please allow 15 minutes so you can see all of the wholesale rates and loan terms available to you. Have pen, paper, and calculator ready when we talk.
If you do not like the loan terms I offer you, you are under no obligation to move forward.
If you like what you see and think I'm the right expert to help you with your investment property financing, we can start by reserving a spot for you on my Funding Calendar for a tentative date to fund your loan.
If you choose another loan source, the information you receive on our call will still help you.
Call 855-774-3160 or schedule a quick WHOLESALE RATE SHOPPER call on my calendar by clicking here. No credit check. No cost. No obligation.