Origination Points Explained: What You're Really Paying for Your DSCR Loan
When comparing DSCR loan offers, most investors focus on one number:
The interest rate.
But your interest rate is only part of the story.
Another cost that can significantly affect your total loan expense is origination points. Understanding how they work can help you compare loan offers more accurately—and avoid paying more than necessary.
What Are Origination Points?
Origination points are fees charged by a lender or mortgage broker for arranging and processing your loan.
Like discount points, they're expressed as a percentage of the loan amount.
One origination point equals 1% of your loan amount.
For example:
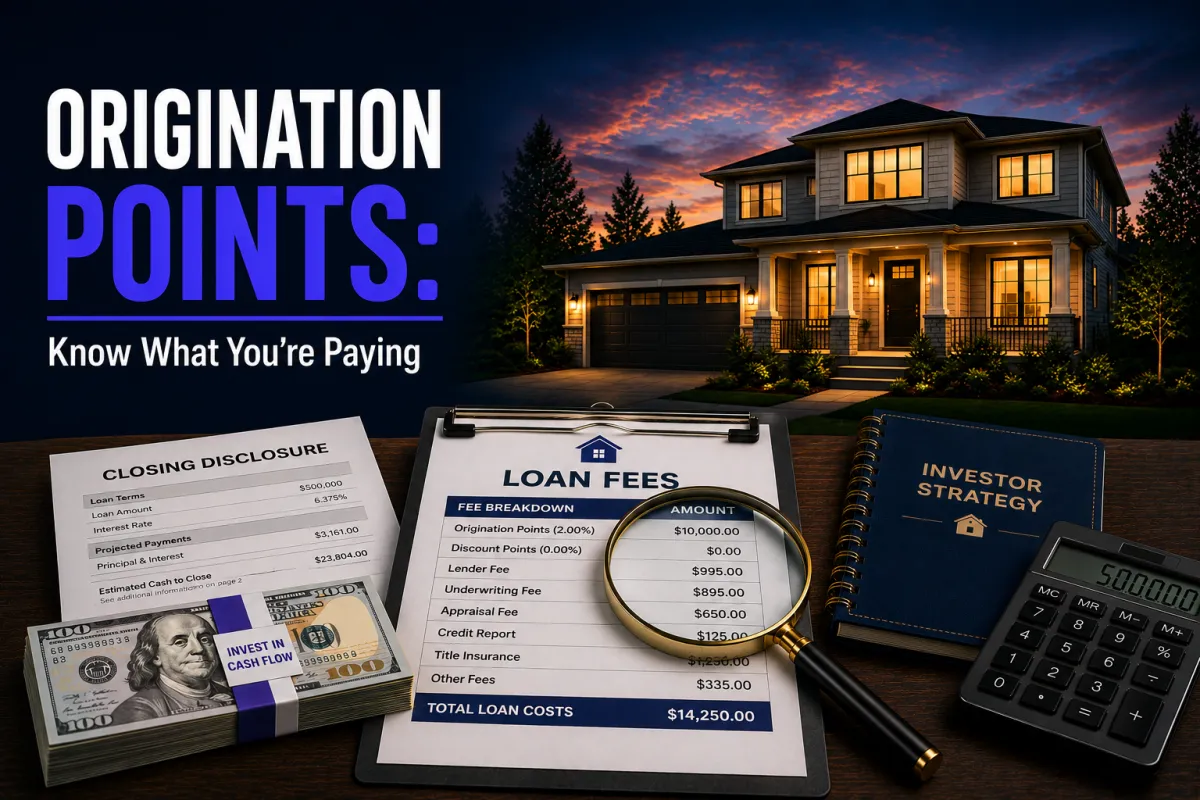
A $500,000 loan with 2 origination points would result in an origination fee of $10,000.
What's Typical?
Origination fees vary by lender, broker, loan program, and loan complexity.
For many DSCR loans, origination charges commonly range from approximately:
1.95% to 5.00% of the loan amount
The amount you pay should always be clearly disclosed before you move forward with your loan.
Why Investors Need to Pay Attention
Some investors compare only interest rates without looking closely at the fees behind them.
That's a mistake.
A loan with an attractive interest rate may come with substantially higher origination charges, discount points, or other closing costs.
By the time those fees become obvious, you've already invested time, submitted documents, paid for an appraisal, and may feel committed to moving forward.
The best loan isn't always the one with the lowest advertised rate—it's the one that provides the best overall value.
Compare the Complete Loan Offer
Whenever you're evaluating financing, don't compare only one number.
Review the complete picture, including:
Interest rate
Discount points
Origination points
Lender fees
Third-party closing costs
Monthly payment
Total cash out or cash required at closing
Only then can you accurately determine which loan is truly the better deal.
Transparency Matters
A professional mortgage loan officer should be willing to explain every fee and answer your questions before you commit.
You should know exactly:
What you're paying
Why you're paying it
Whether there are lower-cost alternatives available
There shouldn't be any surprises at closing.
The Bottom Line
Origination points are a normal part of many DSCR loans, but they shouldn't be overlooked.
Understanding how they're calculated—and comparing them alongside interest rates, discount points, and other loan costs—can save you thousands of dollars and help you make a more informed financing decision.
Before choosing a lender, make sure you understand the complete cost of the loan—not just the interest rate.
Applying For a DSCR Loan?
If you're planning to apply for a DSCR loan, call me, Brian Smith, at 855-774-3160 or schedule a quick WHOLESALE RATE SHOPPER call on my calendar by clicking here.
On the call, you and I will shop your loan scenario with 100+ wholesale lenders to find the ones accepting your scenario and the wholesale rates they're offering you. No credit check needed.
We'll find the lenders offering you the best rate and lowest payment for your DSCR loan scenario, even if your investment property is listed for sale, vacant, bought yesterday, or behind on payments. With my DSCR loan, you can maximize your property's cash flow and bottom line.
Please allow 15 minutes so you can see all of the wholesale rates and loan terms available to you. Have pen, paper, and calculator ready when we talk.
If you do not like the loan terms I offer you, you are under no obligation to move forward.
If you like what you see and think I'm the right expert to help you with your investment property financing, we can start by reserving a spot for you on my Funding Calendar for a tentative date to fund your loan.
If you choose another loan source, the information you receive on our call will still help you.
Call 855-774-3160 or schedule a quick WHOLESALE RATE SHOPPER call on my calendar by clicking here. No credit check. No cost. No obligation.