What Is a DSCR Ratio? A Simple Guide for Real Estate Investors
If you're applying for a DSCR loan, one number matters more than almost anything else: your Debt Service Coverage Ratio (DSCR).
The good news is that it's much simpler than it sounds.
Your DSCR ratio tells a lender whether your property's rental income is enough to cover the monthly mortgage payment. It's one of the primary tools lenders use to evaluate the financial strength of an investment property.
What Is a DSCR Ratio?
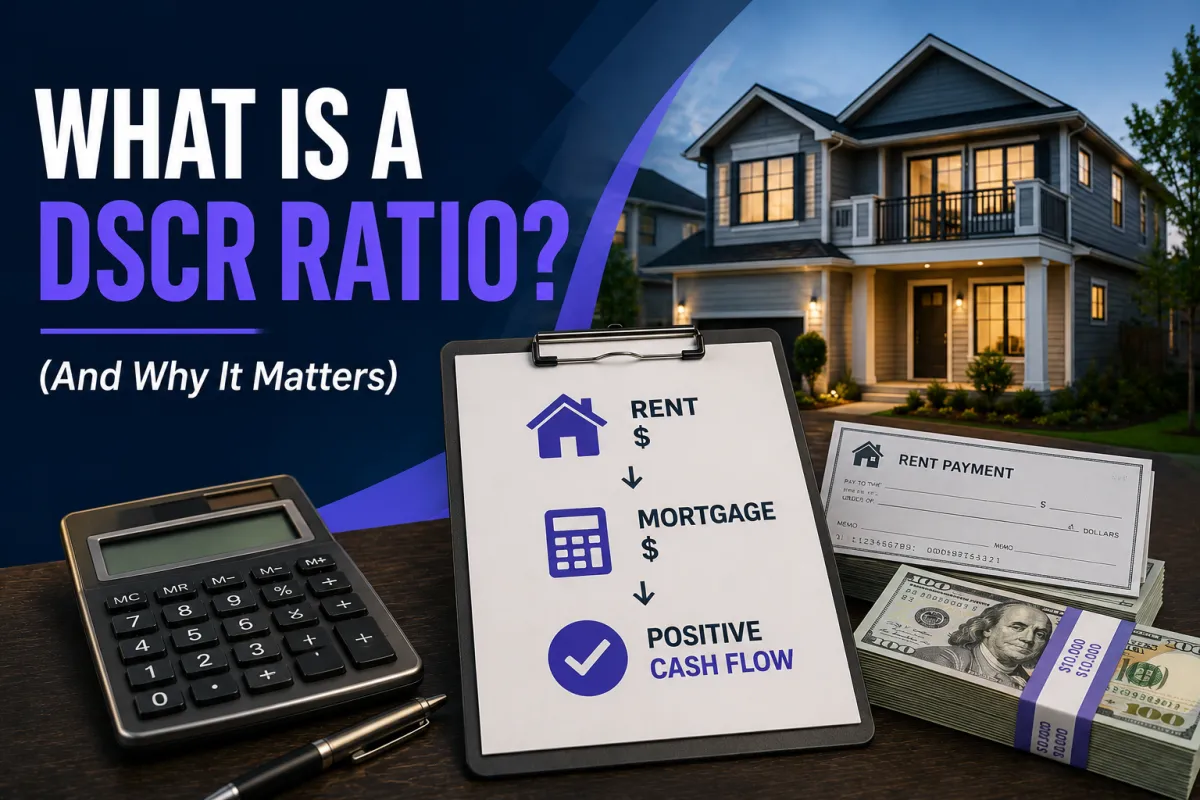
The Debt Service Coverage Ratio compares your property's monthly rental income to its monthly housing expense.
The formula is:
DSCR = Monthly Rental Income ÷ Monthly PITIA
PITIA stands for:
Principal
Interest
Taxes
Insurance
HOA dues (if applicable)
A Simple Example
Let's assume your rental property produces:
Monthly Rent: $2,500
Monthly PITIA: $2,000
Your calculation would be:
$2,500 ÷ $2,000 = 1.25 DSCR
That means your property generates 25% more income than is needed to cover the monthly mortgage payment.
Generally speaking:
Above 1.00 = Positive cash flow
1.00 = Income covers the payment
Below 1.00 = The payment is higher than the property's income
Why Your DSCR Matters
Your DSCR doesn't just affect whether you're approved.
It can also influence:
Your interest rate
Your maximum loan-to-value (LTV)
The amount of cash you can access
Which loan programs are available
In general, stronger DSCR ratios qualify for more favorable loan terms.
What If Your DSCR Is Below 1.00?
Many investors assume they're automatically disqualified if their property doesn't produce enough rental income.
That's not always true.
While many lenders prefer a DSCR of 1.00 or higher, specialized loan programs exist for properties with low DSCR or even no DSCR requirement, depending on the overall loan scenario.
The key is knowing which lenders offer those programs.
The Bottom Line
Your DSCR ratio is one of the most important numbers in an investment property refinance, but it isn't the only factor lenders consider.
A strong DSCR can improve your interest rate, increase your available loan options, and help you qualify for more cash-out. Even if your property's ratio falls below 1.00, financing may still be available through specialized investor loan programs.
Before assuming your property won't qualify, make sure you're comparing multiple lenders. The right loan program can often make the difference between a declined application and a successful closing.
Applying For a DSCR Loan?
If you're planning to apply for a DSCR loan, call me, Brian Smith, at 855-774-3160 or schedule a quick WHOLESALE RATE SHOPPER call on my calendar by clicking here.
On the call, you and I will shop your loan scenario with 100+ wholesale lenders to find the ones accepting your scenario and the wholesale rates they're offering you. No credit check needed.
We'll find the lenders offering you the best rate and lowest payment for your DSCR loan scenario, even if your investment property is listed for sale, vacant, bought yesterday, or behind on payments. With my DSCR loan, you can maximize your property's cash flow and bottom line.
Please allow 15 minutes so you can see all of the wholesale rates and loan terms available to you. Have pen, paper, and calculator ready when we talk.
If you do not like the loan terms I offer you, you are under no obligation to move forward.
If you like what you see and think I'm the right expert to help you with your investment property financing, we can start by reserving a spot for you on my Funding Calendar for a tentative date to fund your loan.
If you choose another loan source, the information you receive on our call will still help you.
Call 855-774-3160 or schedule a quick WHOLESALE RATE SHOPPER call on my calendar by clicking here. No credit check. No cost. No obligation.